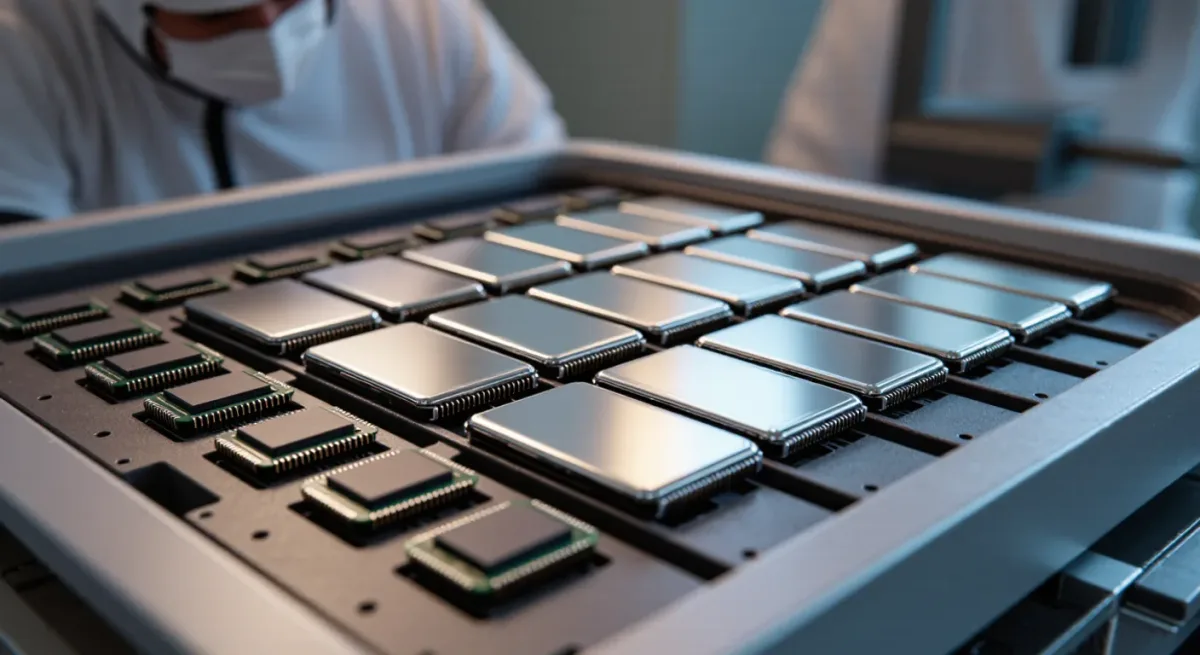
A fabless semiconductor company designs and sells chips but owns no factory. It pays a foundry — a manufacturer that builds chips for many customers — to turn its designs into silicon. The word itself is a mash-up: "fab" means fabrication line, and "less" means the company doesn't have one.
The split matters because a single chip production line is extremely costly, which is why design-focused companies outsource manufacturing entirely, as Samsung's semiconductor glossary explains. Three business models now divide the industry: the integrated device manufacturer (IDM) controls everything from planning to finished product, the foundry only manufactures, and the fabless company only designs. Nvidia, Qualcomm, Broadcom, AMD, and MediaTek all sit in the third group. We covered a connected angle in What a Semiconductor Wafer Is and Why Yields Decide Chip Prices.
Understanding who actually makes a chip explains a lot about who bears the cost, who holds the pricing power, and what happens when capacity runs short — a live question now that Samsung, SK Hynix and Micron have reportedly sold out 2027 memory capacity. For related coverage, see Samsung, SK Hynix and Micron Have Reportedly Sold Out 2027 Memory Capacity.
Why did the fabless model emerge?
Before the 1980s, the semiconductor industry was vertically integrated. Companies owned their own wafer fabrication facilities, developed their own process technology, and handled assembly and testing themselves, according to Wikipedia's history of fabless manufacturing. Building a fab presented high barriers to entry, especially for startups.
Two conditions broke that structure open. First, IDMs had excess production capacity, which gave smaller companies somewhere to send their designs. Second, in 1987, Morris Chang founded Taiwan Semiconductor Manufacturing Company (TSMC) in Taiwan. TSMC became the cornerstone of the model: a pure-play foundry that manufactures for many clients and competes with none of them.
Gordon A. Campbell at Chips and Technologies was among the first to promote the approach in the mid-1980s, at the time outsourcing wafer fabrication to Japan. An even earlier example exists: LSI Computer Systems (LSI/CSI), formed in 1969 by engineers leaving General Instrument Microelectronics, designed custom circuits for Control Data Corporation while relying on outside fab and packaging houses.
How does the fabless model actually work?
The division of labor is clean. The fabless company owns the chip's architecture, its design files, and usually the software ecosystem around it. The foundry owns the fabrication process and the expensive equipment that runs it. The fabless firm sends a mask set — the master pattern for the chip — and the foundry prints it onto wafers.
Nvidia is the textbook case. Since its founding in 1993, the company has focused on chip architecture design and its software stack, not on photolithography tools or cleanrooms, per an explainer on who manufactures Nvidia's chips. TSMC produces the bulk of its most advanced AI and data center chips, with some production at Samsung Foundry in South Korea. Neither foundry owns Nvidia's designs; they fabricate wafers from Nvidia's mask sets and design rules.
The same division explains a common confusion. Nvidia has announced final-stage assembly and testing of Blackwell chips in Arizona and rack integration in Texas — but that is packaging and system integration, not wafer fabrication. No 300mm fabs are being built for Nvidia in the United States.
What does each model cost — and earn?
The economics pull in opposite directions. A fab ties up enormous capital in buildings and equipment, and that capital sits idle when demand dips. A fabless company avoids that fixed cost and can pour its resources into research and development for the end market. The trade-off: it depends entirely on foundry partners for supply, and pays for capacity in good times and bad.
The revenue rankings show how far the model has traveled. Wikipedia's figures, drawn from industry data, list the top five fabless companies by 2024 revenue as Nvidia at $124,377 million, Qualcomm at $34,857 million, Broadcom at $30,644 million, AMD at $25,785 million, and MediaTek at $16,519 million. In 2020, the same ranking was led by Qualcomm at $19,407 million, with Nvidia third at $15,412 million — a reversal that tracks the AI boom landing on a fabless designer.
The model has also absorbed its critics from inside. Wikipedia records that major IDMs including Conexant, Semtech, and LSI Logic converted fully to the fabless model, and that most large IDMs such as Infineon and Cypress now outsource a significant share of manufacturing. When the manufacturers start acting like the outsourcers, the argument is largely settled.
Where does the fabless model break down?
Concentration is the first crack. Fabless firms funnel demand into a small number of foundries, and the most advanced process nodes sit with fewer still. That concentration gives foundries pricing power and leaves designers exposed when capacity tightens. It also concentrates geography: Wikipedia notes that foundries are often located in Taiwan, which turns any regional disruption into a global chip problem.
The second crack is the boundary between fabrication and everything else. Advanced packaging — the step that connects multiple chip dies into one module — sits between the two worlds. Nvidia's multi-die GPU modules depend on TSMC's CoWoS packaging technology, so even a company that has successfully outsourced fabrication can find its bottleneck one step downstream, in a process its foundry controls.
The third is the memory market, where the models blur differently. Memory makers run their own fabs, and when they sell out years of capacity, fabless designers who need that memory in their products have no lever to pull. The supply chain is only as flexible as its least flexible link.
What this means for buyers and the market
Our analysis: the fabless split is best read as a risk transfer, not a cost saving. Fabless companies traded capital risk for supply risk. When demand is strong and foundry capacity is available, the model looks unbeatable — designers compound their R&D spending into products while someone else carries the factories. When capacity is scarce, the designers wait in line like everyone else, and the foundries decide who gets silicon first.
For anyone buying hardware, the practical takeaway is to read the supply chain, not the brand. A chip labeled with a designer's name was almost certainly printed by a foundry, likely in Taiwan, and possibly packaged by yet another company. The brand on the box tells you who designed the silicon; the ledger behind it tells you who can slow it down.
The model's next test is whether the geographic concentration that made it efficient can survive a decade in which governments are paying to rebuild domestic fabrication. Fabless design is portable. Fabs are not.